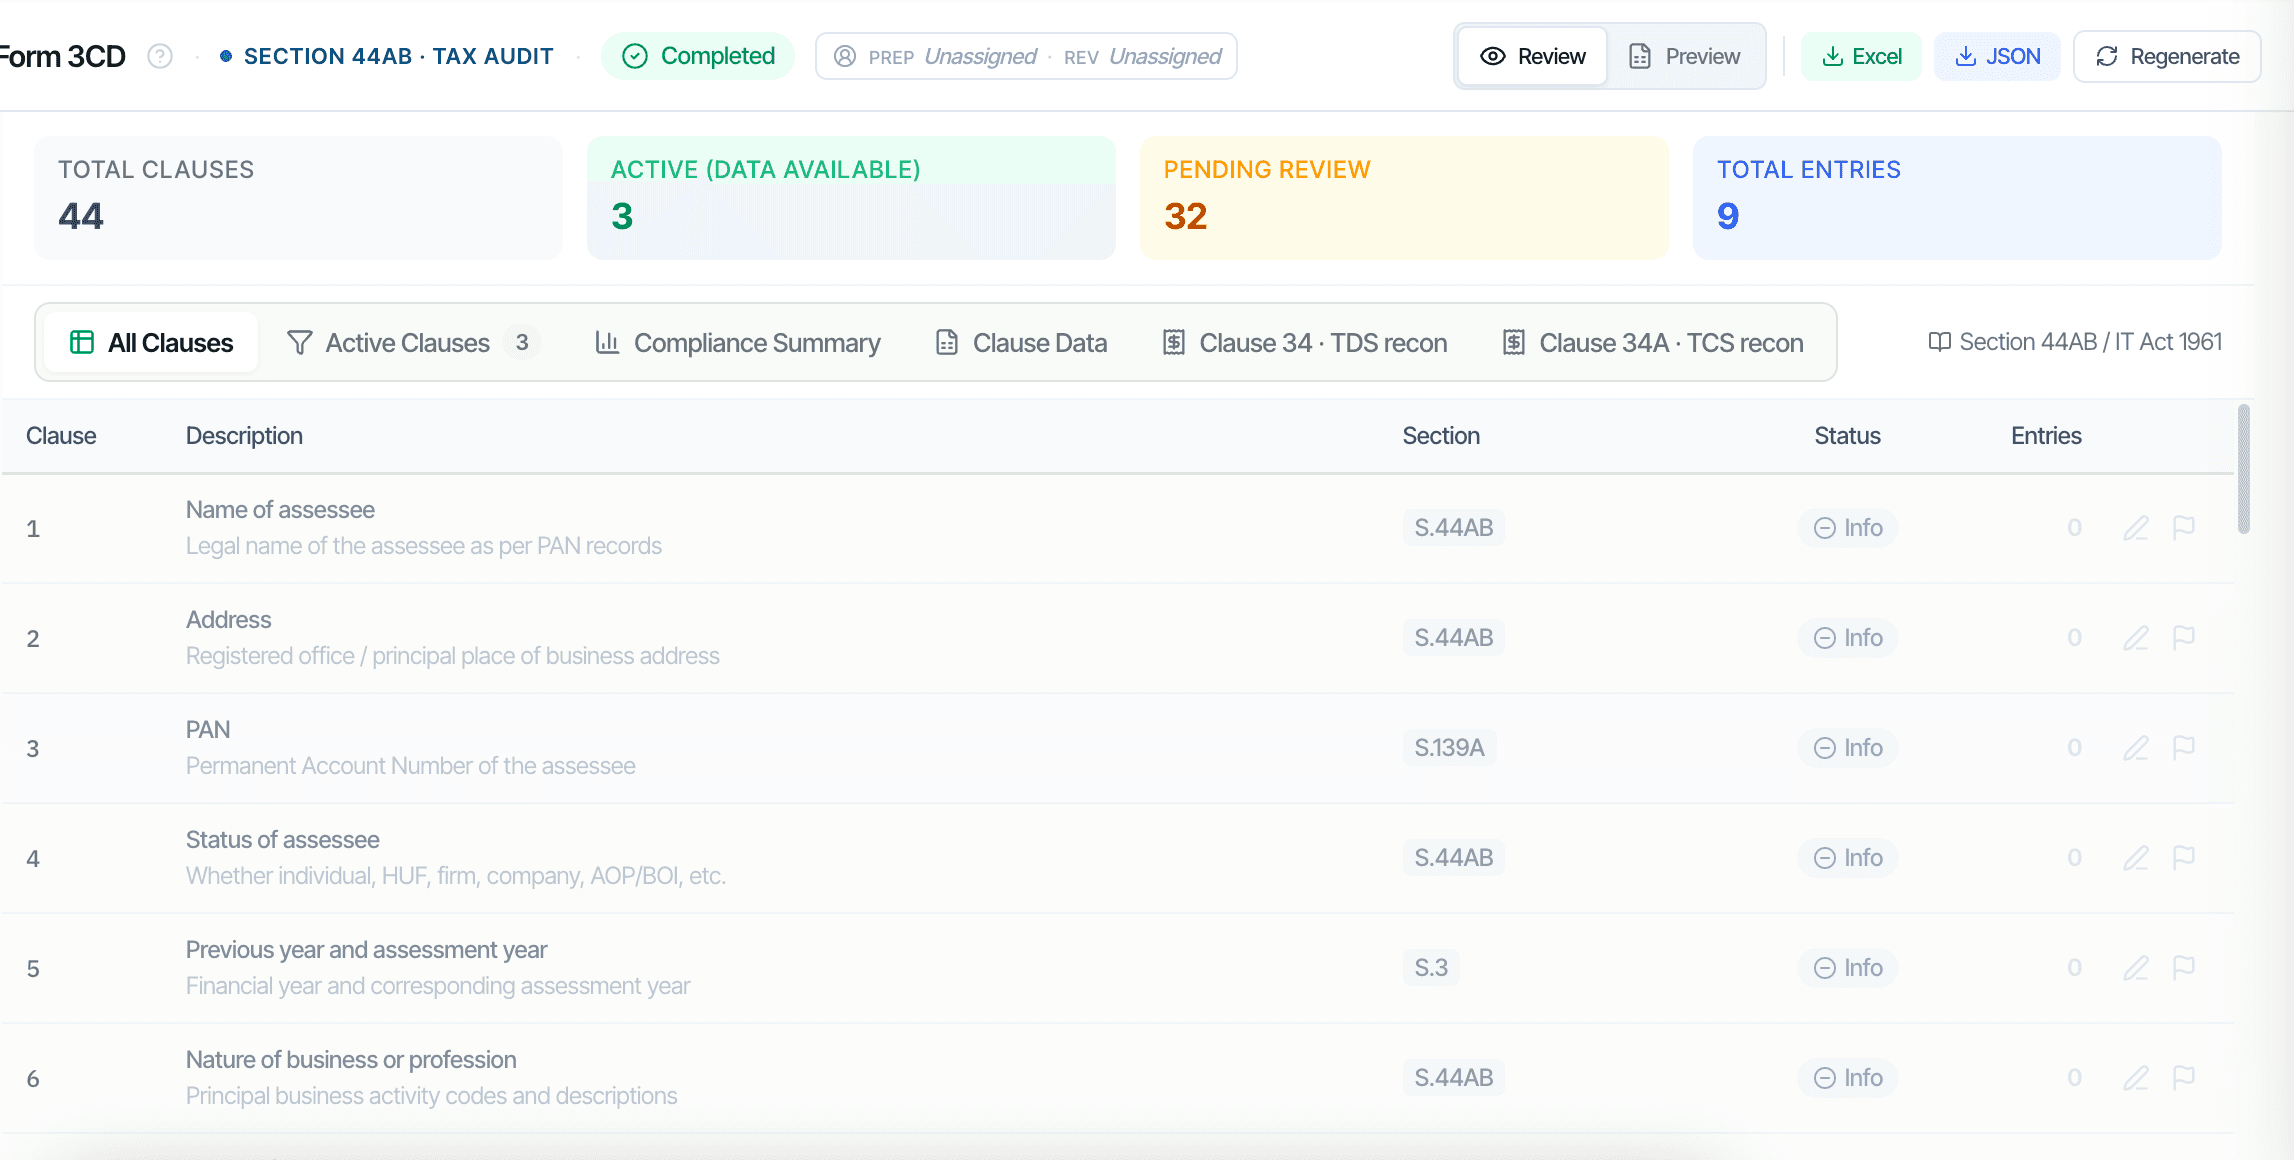
CORAA ಸ್ವಯಂಚಾಲಿತಗೊಳಿಸುತ್ತದೆ data-gathering and ಸಮನ್ವಯ work behind Form 3CD, so your team spends time on judgement, not on copying numbers from Tally to Excel. 55% reduction in ಎಂಗೇಜ್ಮೆಂಟ್ time.
ಪ್ರಮುಖ Form 3CD ಷರತ್ತುಗಳಿಗೆ ಡೇಟಾ ಬೆಂಬಲ - from your Tally ಡೇಟಾ.
Coraa auto-populates the working evidence behind each clause, with traceable links back to the source ಲೆಡ್ಜರ್ entries.
Clause 14
ಲೆಕ್ಕಪತ್ರ ವಿಧಾನ
ನಗದು ಮತ್ತು ವ್ಯಾಪಾರ ಆಧಾರ, ಘಟಕ ಮಟ್ಟದಲ್ಲಿ ವರ್ಗೀಕರಣ.
Clause 15
ವಿಧಾನ ಬದಲಾವಣೆ
ವಿಧಾನ ಬದಲಾವಣೆಯ ಆದಾಯ / ವೆಚ್ಚದ ಮೇಲೆ ಪರಿಣಾಮ.
Clause 18
ಸವಕಳಿ
Block-wise depreciation schedule from ಸ್ಥಿರ ಆಸ್ತಿ ರಿಜಿಸ್ಟರ್.
Clause 21
ಅಂಗೀಕಾರಾರ್ಹವಲ್ಲದವು
Section 40(a) ಅಡಿ ಅಸ್ವೀಕಾರ್ಯ ಮೊತ್ತಗಳು.
Clause 26
Sec 43B ಬಾಕಿಗಳು
Sec 43B ಅಡಿಯ ಶಾಸನಬದ್ಧ ಬಾಕಿಗಳು — ನಿಗದಿತ ದಿನಾಂಕದ ಮೊದಲು ಪಾವತಿಸಬೇಕು, ಇಲ್ಲದಿದ್ದರೆ ಅನುಮತಿ ನಿರಾಕರಿಸಲಾಗುತ್ತದೆ.
Clause 34
TDS / TCS
ಕಡಿತ, ಠೇವಣಿ ಮತ್ತು ಡಿಫಾಲ್ಟ್ ವಿಶ್ಲೇಷಣೆ.
Coraa ಅವುಗಳನ್ನು ಹೇಗೆ ಪರಿಹರಿಸುತ್ತದೆ
One Tally ಆಮದು. ಎಲ್ಲಾ ಕಾರ್ಯವಿಧಾನಗಳು ಏಕಕಾಲದಲ್ಲಿ ನಡೆಯುತ್ತದೆ.
ಲೆಡ್ಜರ್ ಪರಿಶೀಲನೆ across all heads, 100% transaction coverage
GST vs IT turnover ಸಮನ್ವಯ (Clause 29 automation)
TDS ಕಡಿತ ಮತ್ತು ಠೇವಣಿ ಪರಿಶೀಲನೆ (Clause 34)
Section 40(a) ಅಸ್ವೀಕೃತ ವಿಶ್ಲೇಷಣೆ, ಪಾವತಿ ವಿಧಾನ ಮತ್ತು ಸಮಯ
Cash transaction testing, Section 269ST ಅನುಸರಣೆ
Clause 26 ಗಾಗಿ ಸಂಬಂಧಿತ ಪಕ್ಷ ವ್ಯವಹಾರ ಹೊರತೆಗೆಯುವಿಕೆ
ಲೆಡ್ಜರ್ ಪರಿಶೀಲನೆ
8–12h → 2–3h
Plus all ಸಮನ್ವಯಗಳು
GST/TDS ಸಮನ್ವಯ
4–6h → 1h
Form 3CD ಗಾಗಿ
ವರ್ಕಿಂಗ್ ಪೇಪರ್ಗಳು
3–5h → 45m
ಪೂರ್ಣ ಸಾಕ್ಷ್ಯದೊಂದಿಗೆ ರಚಿಸಲಾಗಿದೆ
Section 44AB, answered
The questions auditors actually ask.
No. Data-heavy clauses, depreciation (18), the Sec 43B due-date tests (20, 26), the TDS/TCS tables (34), are computed reproducibly from the imported ledger. Judgement clauses, ICDS (13/14), Sec 37 disallowances (21(a)), deemed dividend (36A), the GST break-up (44), are drafted as candidates with the rule cited, for the auditor to characterise. The engine never concludes them.
Property transfers are checked against the stamp-duty value where that data is available, and any shortfall is surfaced for the auditor's review. This is a books-and-register check, not a substitute for the stamp-duty valuation itself.
No, they're separate. Related-party transactions under Sec 40A(2)(b) feed Clause 23; statutory dues under Sec 43B, PF, ESI, GST, TDS, feed Clause 26. CORAA keeps the two distinct so a review doesn't conflate them.
The confirmed report is produced in three forms that agree, the e-filing JSON schema-validated against the current utility, a government-format workbook, and a DOCX, so the JSON you upload reconciles to the workbook you review and the report you file.
The auditor is. CORAA computes, cites and drafts, but every clause is a candidate awaiting confirmation, and it never signs. The engine does the work; the auditor decides.
Data is hosted in India, handled in line with the DPDPA, on ISO 27001-certified infrastructure. Client data is never used to train shared or third-party models.
ಗಡುವನ್ನು ಗೆಲ್ಲಿರಿ
ಇನ್ನಷ್ಟು clients, better quality, ಅದೇ ಸೆಪ್ಟೆಂಬರ್.
ಉಚಿತ ಪ್ರಯೋಗ — ಮೊದಲ ಆಡಿಟ್ ನಮ್ಮ ಕಡೆಯಿಂದ. ಭಾರತದಲ್ಲಿ ಹೋಸ್ಟ್ ಮಾಡಲಾಗಿದೆ. DPDPA ಅನುಸರಣೆ.