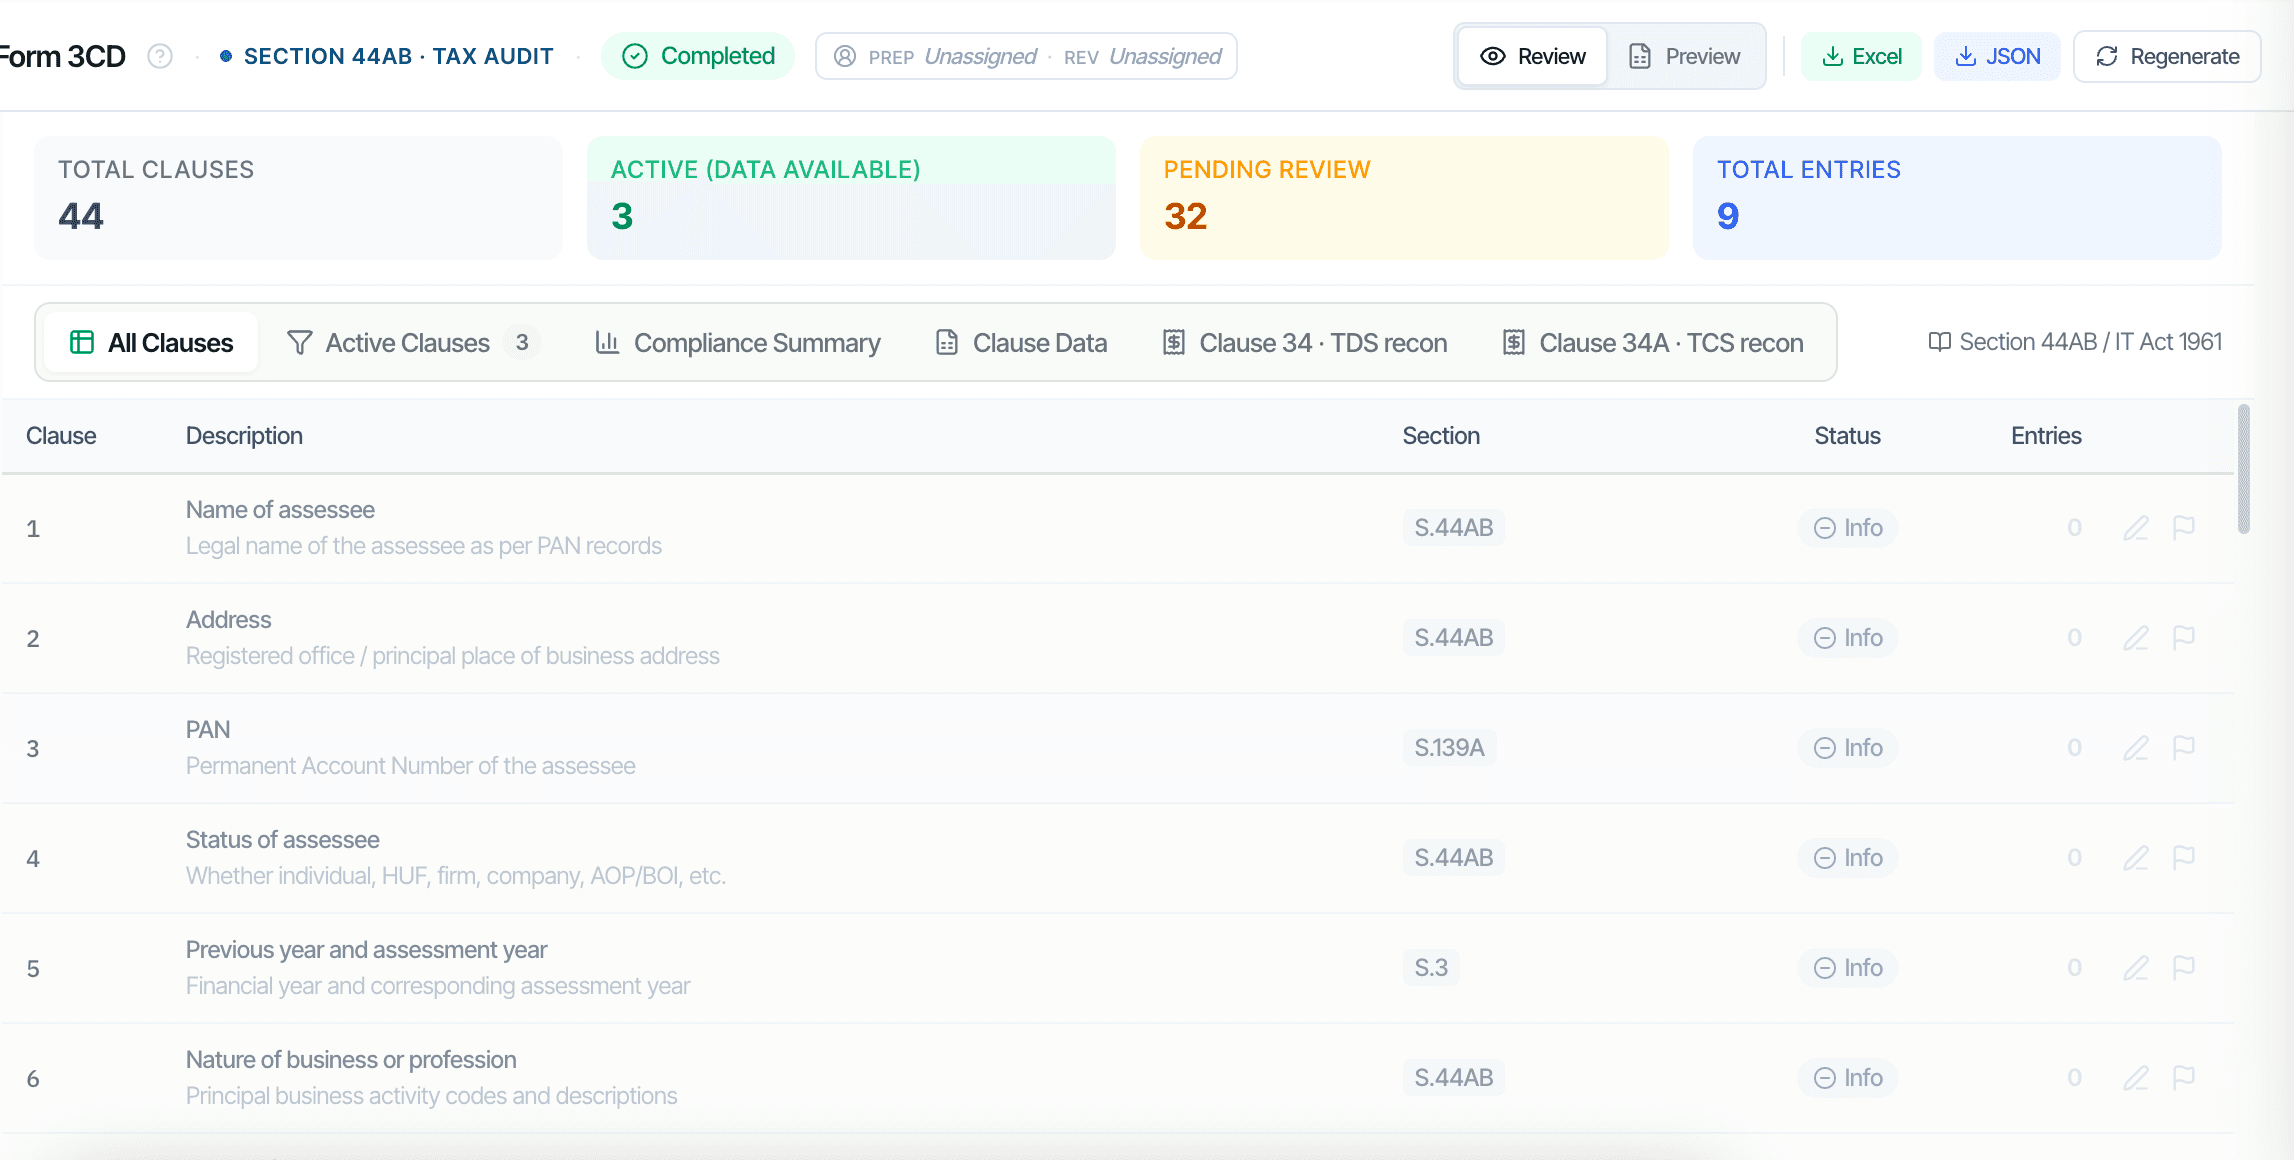
பிரிவு 44AB வரிக் கணக்காய்வு, செப்டம்பருக்கு தயார்.
CORAA தானியக்கமாக்குs the data-gathering and ஒத்திசைவு work behind Form 3CD, so your குழு spends time on judgement, not on copying numbers from Tally to Excel. 55% reduction in எங்கேஜ்மென்ட் time.
முக்கிய Form 3CD உட்பிரிவுகளுக்கு தரவு ஆதரவு - உங்கள் Tally தரவிலிருந்து.
Coraa auto-populates the working ஆதாரம் behind each clause, with traceable links back to the source ledger entries.
Clause 14
கணக்கியல் முறை
பணம் எதிர் வணிக அடிப்படை, நிறுவன அளவில் வகைப்பாடு.
Clause 15
முறையில் மாற்றம்
முறை மாற்றத்தின் வருமானம் / செலவு மீதான விளைவு.
Clause 18
தேய்மானம்
நிலையான சொத்து பதிவேட்டிலிருந்து தொகுதி வாரியான தேய்மான அட்டவணை.
Clause 21
ஏற்க இயலாதவை
Amounts inadmissible under பிரிவு 40(a).
Clause 26
Sec 43B நிலுவைகள்
Sec 43B-இன் கீழ் சட்டப்பூர்வ நிலுவைகள் — உரிய தேதிக்கு முன் செலுத்தப்பட வேண்டும், இல்லையெனில் அனுமதி மறுக்கப்படும்.
Clause 34
TDS / TCS
கழிப்பு, வைப்பு மற்றும் தவறுதல் பகுப்பாய்வு.
Coraa எப்படி அவற்றை அணுகுகிறது
ஒரு Tally இறக்குமதி. அனைத்து நடைமுறைகளும் ஒரே நேரத்தில் இயங்குகின்றன.
பேரேடு ஆழ்ந்த ஆய்வு across all heads, 100% பரிவர்த்தனை கவரேஜ்
GST vs IT turnover ஒத்திசைவு (Clause 29 தானியக்கம்)
TDS deduction and deposit சரிபார்ப்பு (Clause 34)
பிரிவு 40(a) disallowance analysis, payment mode and timing
Cash transaction testing, பிரிவு 269ST compliance
Clause 26-க்கான தொடர்புடைய தரப்பு பரிவர்த்தனை பிரித்தெடுத்தல்
பேரேடு ஆழ்ந்த ஆய்வு
8–12h → 2–3h
Plus all ஒத்திசைவுs
GST/TDS ஒத்திசைவு
4–6h → 1h
Form 3CD-க்காக
பணிக்காகிதங்கள்
3–5h → 45m
Generated with full ஆதாரம்
Section 44AB, answered
The questions auditors actually ask.
No. Data-heavy clauses, depreciation (18), the Sec 43B due-date tests (20, 26), the TDS/TCS tables (34), are computed reproducibly from the imported ledger. Judgement clauses, ICDS (13/14), Sec 37 disallowances (21(a)), deemed dividend (36A), the GST break-up (44), are drafted as candidates with the rule cited, for the auditor to characterise. The engine never concludes them.
Property transfers are checked against the stamp-duty value where that data is available, and any shortfall is surfaced for the auditor's review. This is a books-and-register check, not a substitute for the stamp-duty valuation itself.
No, they're separate. Related-party transactions under Sec 40A(2)(b) feed Clause 23; statutory dues under Sec 43B, PF, ESI, GST, TDS, feed Clause 26. CORAA keeps the two distinct so a review doesn't conflate them.
The confirmed report is produced in three forms that agree, the e-filing JSON schema-validated against the current utility, a government-format workbook, and a DOCX, so the JSON you upload reconciles to the workbook you review and the report you file.
The auditor is. CORAA computes, cites and drafts, but every clause is a candidate awaiting confirmation, and it never signs. The engine does the work; the auditor decides.
Data is hosted in India, handled in line with the DPDPA, on ISO 27001-certified infrastructure. Client data is never used to train shared or third-party models.
கடைசி தேதியை வெல்லுங்கள்
More வாடிக்கையாளர்கள், better quality, அதே செப்டம்பர்.
இலவச சோதனை — முதல் கணக்காய்வு எங்கள் செலவில். இந்தியாவில் ஹோஸ்ட் செய்யப்பட்டது. DPDPA இணக்கம்.